Oil & Gas
Nigeria: FG Calls for more Private Investment in Oil Refining
Nigeria's push for private capital in refining and gas confronts a recurring question from investors: not whether the resources exist, but whether the returns do.
The Federal Government, through the Petroleum Technology Development Fund (PTDF), has called for stronger private sector participation in Nigeria's midstream and downstream petroleum sectors, saying rising crude production must be matched with investment in refining, gas processing, pipelines, storage and logistics.
Minister of State for Petroleum Resources (Oil) Heineken Lokpobiri made the call at the inaugural 2026 Petroleum Technology Development Fund Journal Summit on Wednesday in Abuja, themed "Private Sector Participation in Nigeria's Midstream and Downstream Petroleum Sector: Prospects, Challenges and the Way Forward."
Represented by his Technical Adviser, Emmanuel Sinime, Lokpobiri said Nigeria's crude production has risen from about 1 million barrels per day in 2023 to more than 1.7 million barrels per day, while active drilling rigs have increased from about 14 to over 60.
"The federal government, under the able leadership of His Excellency Bola Tinubu, recognises that sustainable development of the Nigerian petroleum sector requires strong and vibrant private sector participation.
The government's role is to establish and enable a policy and regulatory environment, provide strategic directions, and ensure transparency and accountability," Lokpobiri said.
"The ongoing reforms in the petroleum sector are therefore designed to restore investors' confidence, improve regulatory certainty, and create conditions for sustainable private sector investment across the oil and gas value chain."
Upstream gains mean little without downstream infrastructure
Lokpobiri said growth in upstream production would have limited impact if Nigeria fails to develop the infrastructure needed to transport, store, refine and distribute petroleum products efficiently.
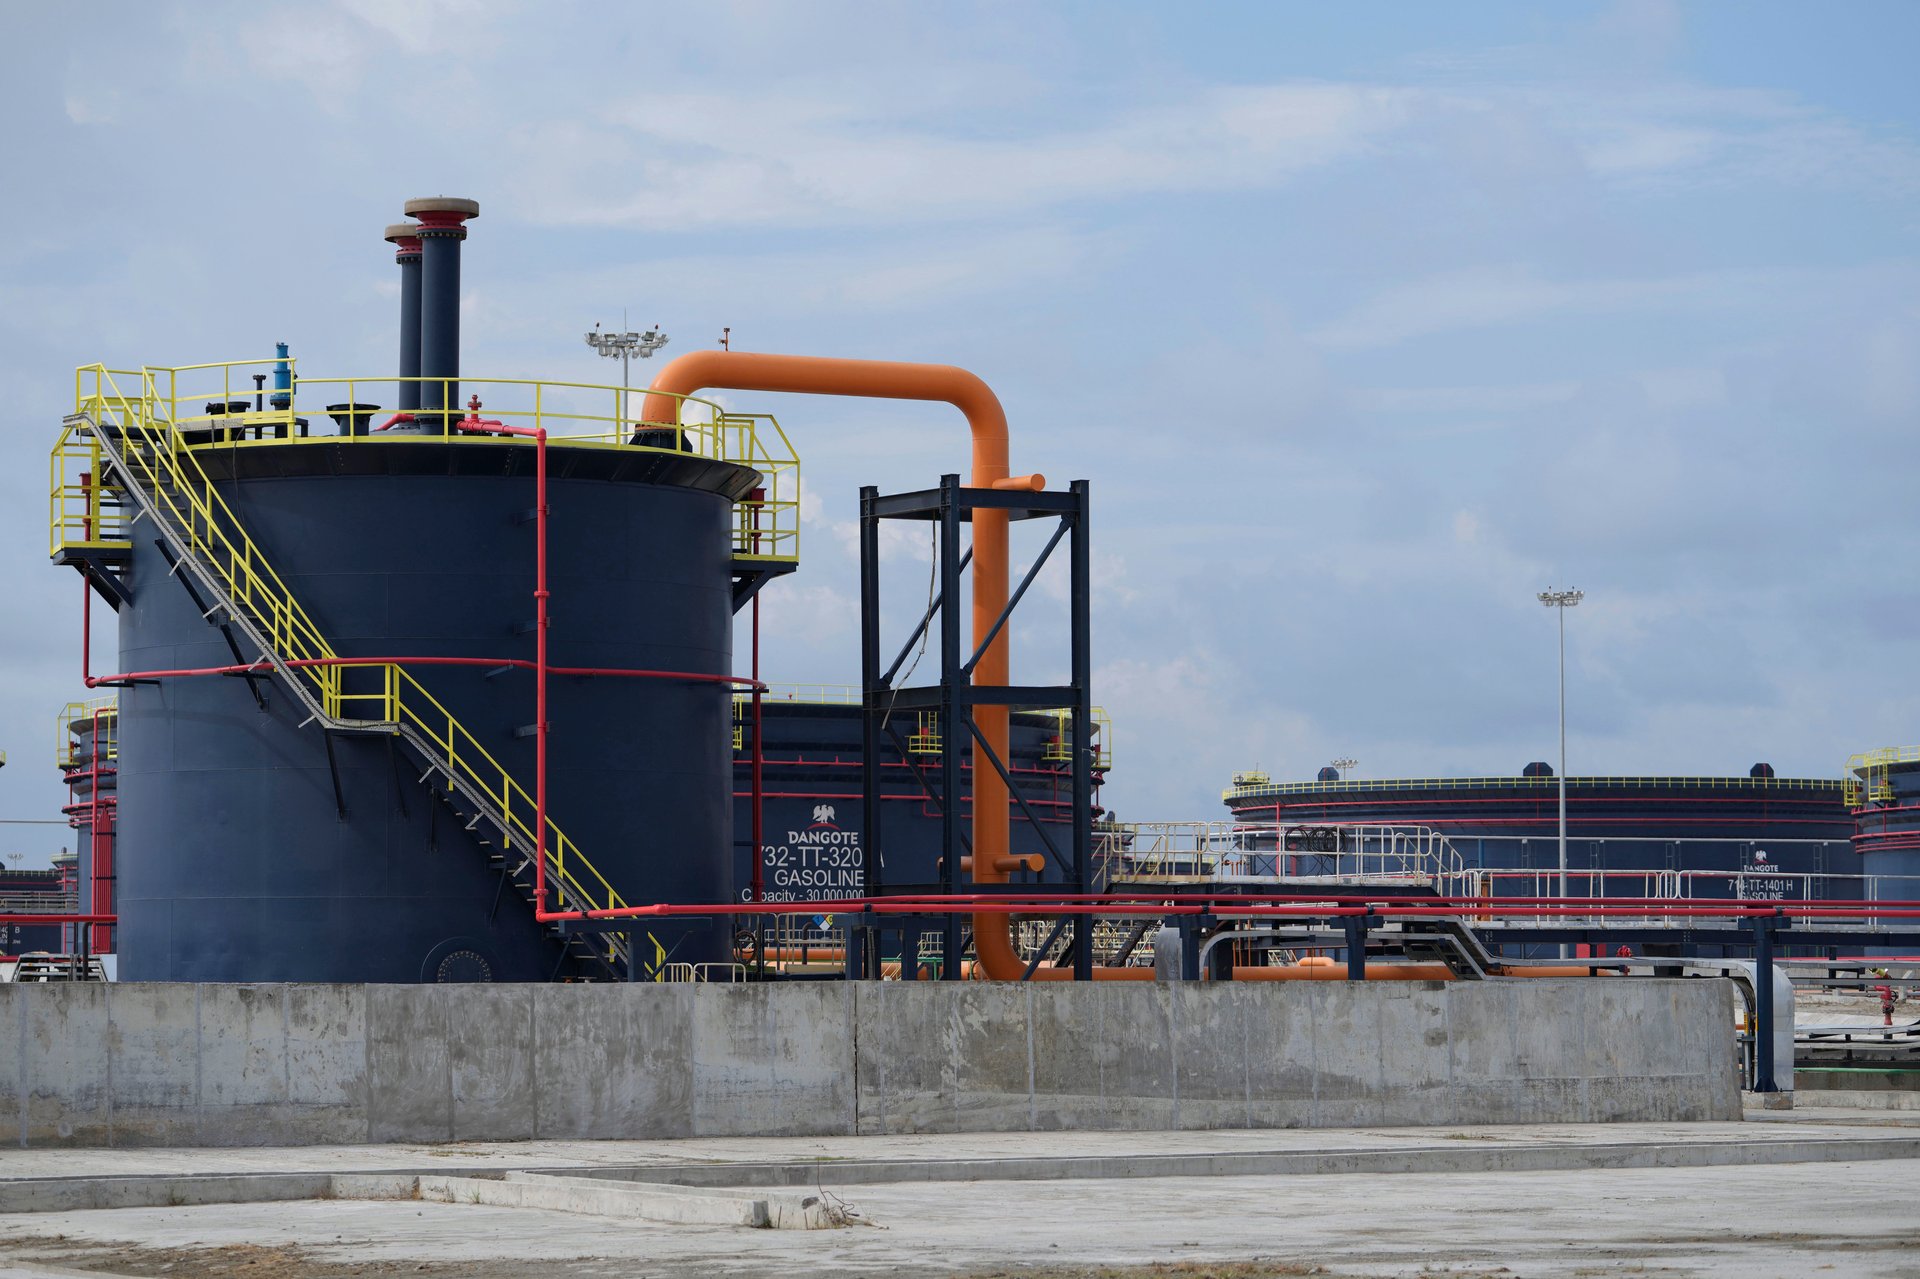
He pointed to the emergence of the Dangote Petroleum Refinery and the expansion of modular refineries, including Waltersmith and Aradel, as evidence of what private investment can do to reshape the downstream sector.
"Increased production must be matched by adequate infrastructure, efficient transportation and storage systems, expanded refining capacity, and a competitive market that delivers value to consumers and investors," he said.
He added that the government is working through the Nigerian Midstream and Downstream Petroleum Regulatory Authority to improve domestic gas pricing, develop rules against anti-competitive practices, and promote fair access to pipelines, depots and terminals.
However, he warned that infrastructure deficits, logistics costs, regulatory uncertainty, market volatility and financing challenges remain major obstacles to investment.
"The issue will not judge us by the number of regulations that we issue or guidelines that we actually publish, but history will judge us by the number of businesses we actually inflate, the investment that we actually attract, the benefits of life that come out of these regulations," he said.
Gas minister stresses need for private capital
Minister of State for Petroleum Resources (Gas) Ekperikpe Ekpo said private capital is critical to unlocking Nigeria's gas resources, pointing to the Petroleum Industry Act as a framework for improving regulatory certainty and the government's Decade of Gas Initiative as a push to use gas for industrialisation, job creation, energy security and economic diversification.
He said Nigeria must attract investment into gas processing, transportation and distribution, as well as LPG, CNG, petrochemicals and other gas-based industries.
"The federal government cannot achieve this objective alone. We must continue to deepen collaboration with private investors, financial institutions, technology providers, and other stakeholders to mobilise the capital and expertise required to deliver these projects," he said, citing infrastructure gaps, high financing costs, project development risks, regulatory bottlenecks and inadequate access to reliable energy infrastructure as key challenges facing investors.
He also urged the PTDF to deepen collaboration with universities, research institutions and industry operators so research can produce practical, commercial solutions.
PTDF frames summit as a bridge to the industry
PTDF Executive Secretary Shuaibu Aliyu said the inaugural summit was designed to extend discussions in the Petroleum Technology Development Journal beyond its pages into a platform for practical industry solutions, describing the journal as a bridge between researchers, academics, industry professionals and policymakers.
The fund's intervention repository currently records 15,639 sponsored scholars and more than 1,700 research items.
"The growing involvement of private investors in refining, gas processing, logistics, storage, and the distribution of petroleum products present substantial opportunities for economic growth, job creation, technology development, and building local capacity," Aliyu said, adding that financing, infrastructure, regulatory certainty, access to technology, market efficiency and technical capacity remain challenges requiring open discussion.
Industry voice flags a shift from training to retaining talent
In his keynote address, Waltersmith Petroman Oil Managing Director Oladapo Filani said Nigeria's challenge has moved beyond producing skilled manpower to retaining that expertise and converting it into technology, businesses and economic value.
"The challenge is no longer simply to produce skilled Nigerian; it is to retain that expertise, create opportunities to apply it and to convert knowledge into technology, businesses and economic value," he said, noting that PTDF has sponsored more than 15,639 scholars and supported over 50,000 research projects, but arguing that the industry's changing structure demands a new approach to human capital development.
Filani said Nigeria needs engineers, project managers, process specialists and commercial professionals capable of operating increasingly complex refineries, gas plants, pipelines and other energy infrastructure.
"For private investors, the central issue is not simply whether Nigeria has significant oil and gas resources, but whether projects can generate predictable, competitive, risk-adjusted returns," he said.
He advocated an integrated energy ecosystem in which shared pipelines, gas processing, storage, power and logistics infrastructure serve multiple operators and industries.
"This is not integration for its own sake. It is about connecting different parts of the value chain in ways that can improve economics, create market access, reduce infrastructure constraints and generate additional value to all stakeholders," he said.
Related Stories
Sign up for our newsletter.
Get the latest news, expert analysis, and industry insights delivered straight to your inbox. Join thousands of professionals shaping the future of energy.
By submitting my information, I agree to the Privacy Policy and Terms of Service.